Physical stock verification (commonly known as stock-taking or annual inventory audit) is a mandatory annual administrative responsibility for academic libraries in universities, colleges, and research institutes across India. Far beyond a mere clerical audit, a well-executed stock verification identifies missing volumes, updates catalog records, reveals damaged or mutilated books requiring conservation or binding, and ensures statutory compliance under General Financial Rules (GFR Rule 215). This guide outlines the official regulatory norms, permissible loss tolerances, comparative methodology, and step-by-step procedures to conduct clean, efficient stock verification.
1. Statutory Norms: Frequency of Stock Verification under GFR
In government, aided, and statutory higher education institutions, stock verification is governed by Rule 215 of the General Financial Rules (GFR), Government of India:
Annual Verification
Physical verification of the entire collection must be conducted every year.
Once in 3 Years
Physical verification of all books should be conducted at least once in three years.
Continuous / Sample Cycle
Continuous verification covering at least one-third (33%) of the collection annually, completing full cycle in 3 years, or sample audit of 10% randomly selected areas.
2. Permissible Loss Tolerances under GFR Rule 215(3)
Unlike standard store inventory (where loss is viewed as negligence or pilferage), open-access libraries recognize that active usage inevitably leads to wear, misplacement, and occasional loss. GFR Rule 215(3) and UGC norms explicitly establish clear loss thresholds:
Standard Statutory Loss Margin Formula:
"Loss of not more than 5 volumes per 1,000 volumes issued and/or consulted in a year in an open-access library shall be taken as reasonable and written off by the competent authority, provided such loss cannot be attributed to dishonesty or negligence."
Note: For rare books, out-of-print manuscripts, high-value art collections, and costly reference compendia, strict individual inquiry is required before any write-off is considered.
3. Comparison of Stock Verification Methods
| Method | Mechanism | Speed & Accuracy | Library Disruption |
|---|---|---|---|
| 1. Accession Register Tally | One person calls accession number from shelf; another ticks mark in physical register. | Slow, prone to register wear and manual tally errors. | High (Requires library closure or halted circulation). |
| 2. Shelf List Card Method | Staff carry physical shelf-list cards to stacks and compare volume-by-volume. | Moderate accuracy; detects misplaced call numbers easily. | Moderate. |
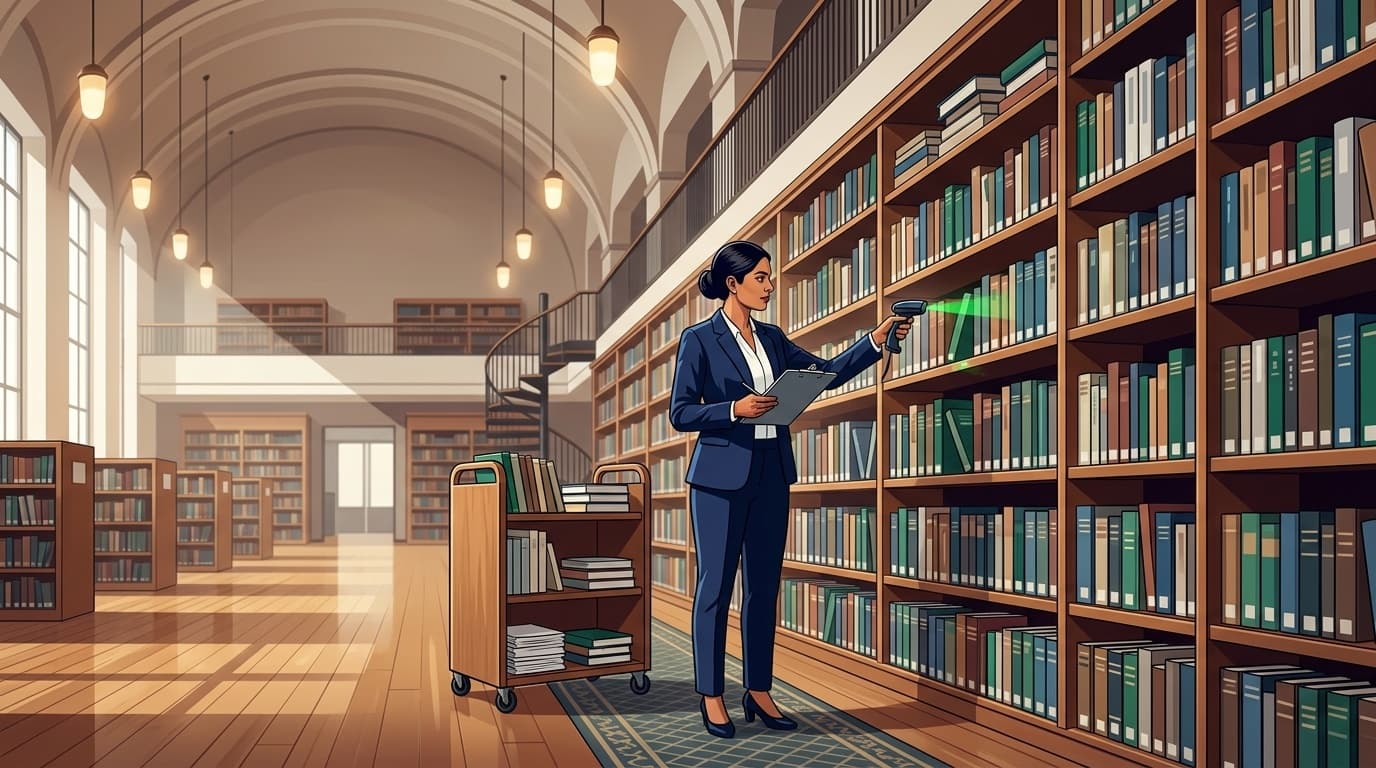
| 3. Automated Barcode Scanning | Cordless handheld barcode scanners or batch data-collectors sweep shelf items directly into LISWALA Stock Verification software. | Fast (1,000+ books/hour), 100% accurate numeric audit. | Zero closure required. Real-time reconciliation with ILMS. |
| 4. RFID Wand Scanner | Handheld RFID reader waved across book spines without pulling volumes from shelves. | Ultra-fast (5,000+ books/hour), identifies shelf-order anomalies. | Minimal. Requires RFID tagged collection. |
4. Step-by-Step Stock Verification Workflow
1 Constitution of Stock Verification Committee
The Principal/Registrar formally constitutes a Stock Verification Committee comprising faculty representatives from various departments, the Librarian (Convener), and nominated library staff.
2 Shelf Preparation & Preliminary Sweep
Conduct systematic shelf-rectification before scanning. Return all loose books from reading tables, cataloging cubicles, and binding queues to their designated stack locations.
3 Systematic Physical Scanning
Scan every physical volume on the shelf sequentially using barcode scanners. Collect accession lists by bay, rack, or classification range into the LISWALA Stock Verification Tool.
4 Reconciliation with Circulation and Administrative Lists
Cross-reference the scanned list with active patron loans in your ILMS (KOHA), books sent for commercial binding, interlibrary loans, and departmental branch libraries.
5 Report Compilation & Write-Off Resolution
The committee compiles the final verification report showing: Total accessioned collection, Verified on shelf, Verified on loan/bindery, Discrepancies, and Unaccounted losses compared against GFR Rule 215 permissible margin.
Audit Readiness & Accreditation Impact
A documented, systematic stock verification report is an essential prerequisite during NAAC peer visits (Criterion 4.2), statutory government audits, and ISO certification reviews. Utilizing modern automated tools like LISWALA eliminates weeks of manual drudgery, ensuring institutional transparency and flawless collection accounting.